The Nigerian government’s recent economic reforms have contributed to stabilizing the country’s financial system, according to economic analysts. However, these improvements have not translated into relief for ordinary citizens, who continue to face significant financial pressures.
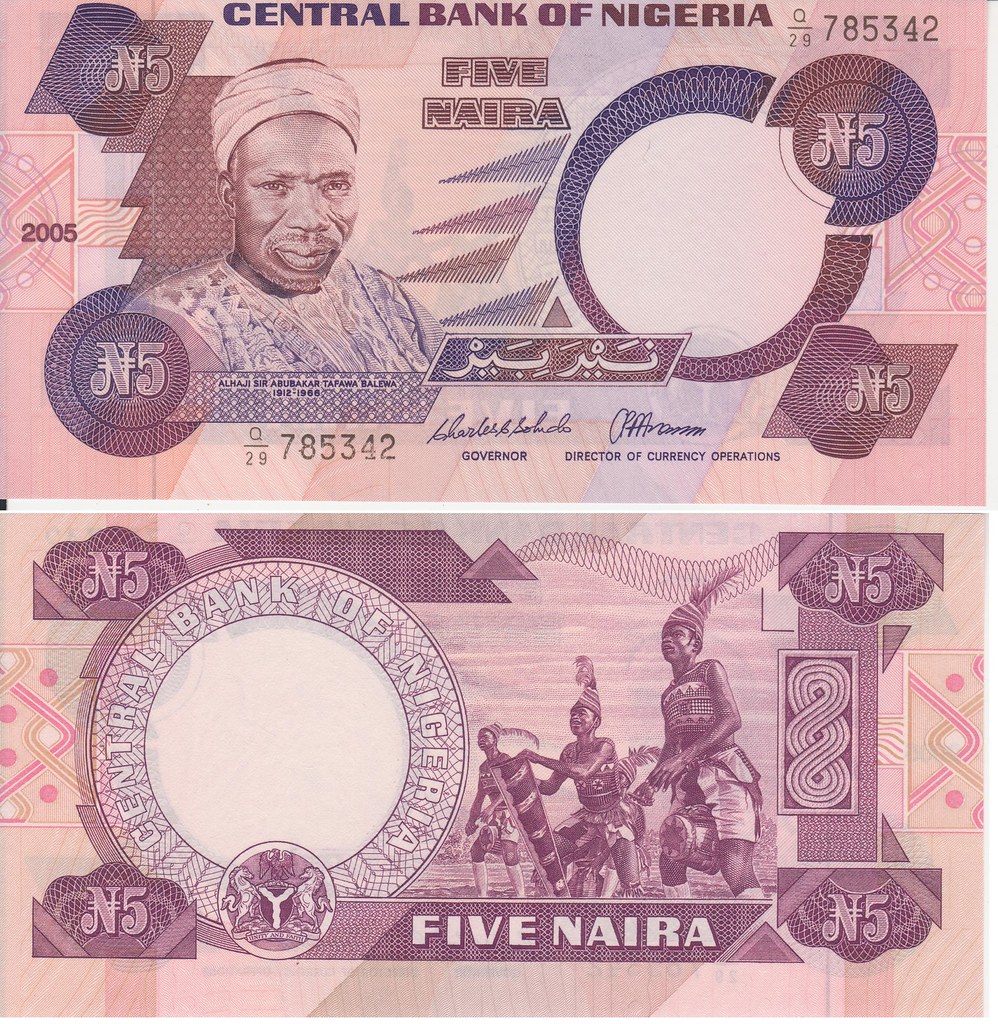
The reforms, which include measures to curb inflation and improve fiscal discipline, have helped maintain macroeconomic stability. Inflation, which had reached double digits earlier this year, has since fallen to a more manageable level. The Central Bank of Nigeria has also maintained a stable exchange rate, which has supported trade and investment.
Despite these positive developments, household incomes have not kept pace with the cost of living. Many Nigerians, particularly in urban areas, report increased difficulty in meeting basic needs such as food and utilities. A recent survey by a local think tank found that over 60% of respondents experienced a decline in their standard of living since the start of the year.
The economic challenges are compounded by ongoing structural issues, including high unemployment and a reliance on oil exports. While the government has introduced policies to diversify the economy, the effects have not yet been fully realized.
This situation reflects a common challenge in many developing economies: the gap between macroeconomic stability and real-life economic conditions. As the reforms continue, the focus remains on how to ensure that the benefits of economic growth are more evenly distributed across society.